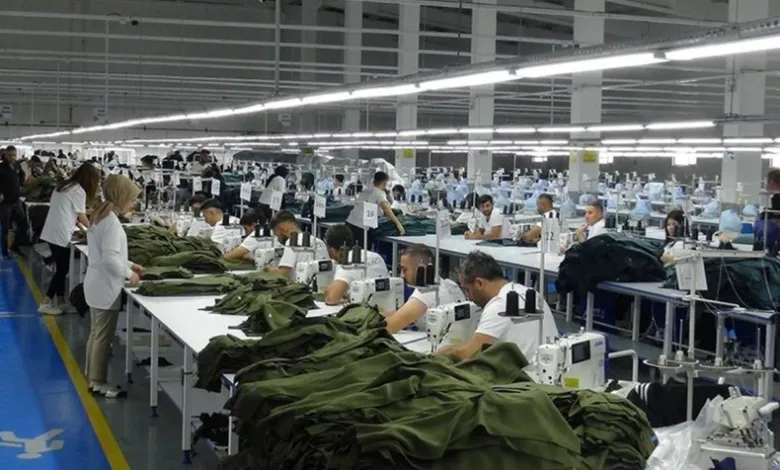
Recent Index of Industrial Production (IIP) data highlights a sharp divergence across India's textile ecosystem, as upstream fiber and fabric manufacturing expands while downstream apparel output faces continuous pressure. Upstream textile production posted a robust 11.9 per cent cumulative rise, driven by stable domestic fiber utilization and replenishment cycles among weaving networks. Conversely, wearing apparel output contracted by 5.6 per cent, reflecting subdued foreign sourcing and lengthened order cycles from key North American and European retail destinations.
Strategic realignment in spinning and weaving operations
The disparity presents operational challenges for garment manufacturers navigating higher input fabric costs alongside constrained finished-goods pricing. However, integrated mill operators leverage advanced technical textiles and recycled fiber blends to maintain operating margins. Upstream facilities are capitalizing on domestic fabric demand, but downstream exporters require accelerated trade agreements to clear finished garment inventories, stated RK Sharma, Senior Trade Analyst, Apex Textile Insights.
Sourcing diversification opens new capital opportunities
Despite near-term apparel export headwinds, long-term expansion remains supported by capital investments under the PM MITRA park scheme and rising domestic garment consumption. Manufacturers upgrading cut-and-sew technology and expanding regional retail supply links remain well-positioned to bridge the value chain divide as global retail inventories rebalance.
Measuring national output across yarn, woven fabrics, and finished garments, official industrial production indexes track manufacturing health across domestic hubs. With long-term growth targeting $250 billion in national textile production by 2030, the sector leverages federal infrastructure investments to reinforce global trade competitiveness.